Chapter 1: How Mortgages Work
US banking, mortgage pricing, and interest-rate risk.
The rate of interest acts as a link between income-value and capital-value.
- Irving Fisher
Chapter Overview
- How mortgages started as simple secured loans and became the modern US home loan
- What a mortgage-backed security is: a bundle of home loans turned into an investable security
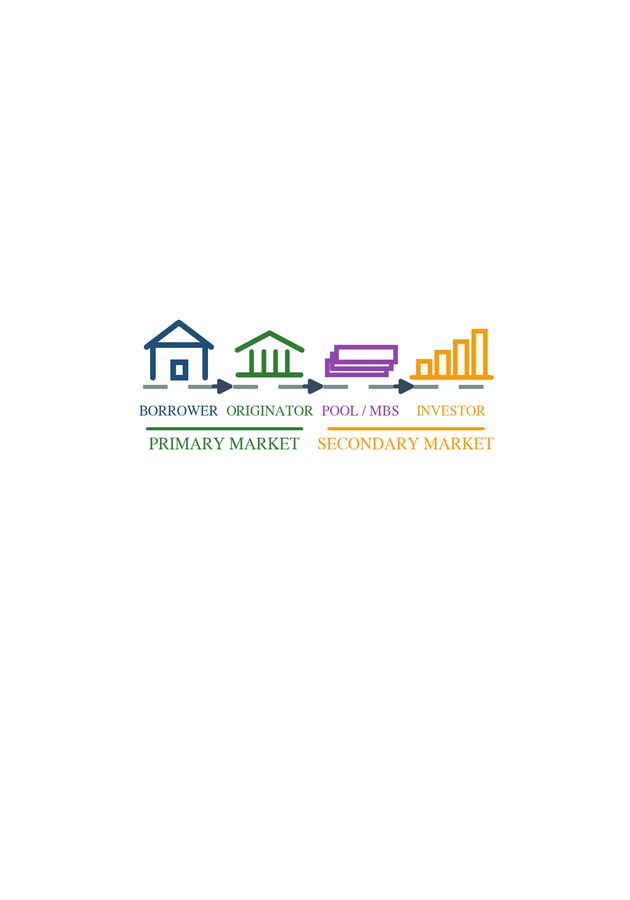
- How a single mortgage loan becomes a pool, an MBS, and sometimes a CMO structure
- How servicing rights and cash-flow waterfalls fit into the mortgage stack
- How adjustable-rate mortgages and balloon loans differ from the standard fixed-rate loan
- Who the main players are in the US mortgage market and what each one does
- How the retail, wholesale, and correspondent origination channels differ, and why the channel changes how a pool prepays
- What makes a loan agency-eligible, and how conforming loans differ from jumbo loan and other non-agency credit
- How a fixed-rate mortgage is paid down month by month, which is called amortization
- How WAC, WALA, WAM, and Pool Factor aggregate individual loans like Jack's into a pool
- What a retail investor can actually buy, and why most already own agency MBS without knowing it
If you are new to the topic, keep three ideas in mind while reading: a mortgage is a loan with monthly payments, the borrower can often pay it off early, and that early payoff changes the value of the loan.
The easiest way to follow the chapter is to think about Jack, a homebuyer who needs a loan. He does not have the full purchase price in cash, so he borrows from a bank and agrees to make the same payment every month. Each payment chips away at what he owes. If rates fall later, Jack may refinance into a cheaper loan and pay the old one off early. That simple path from house purchase to monthly payment to possible refinance is the starting point for everything in this chapter.
Cast:
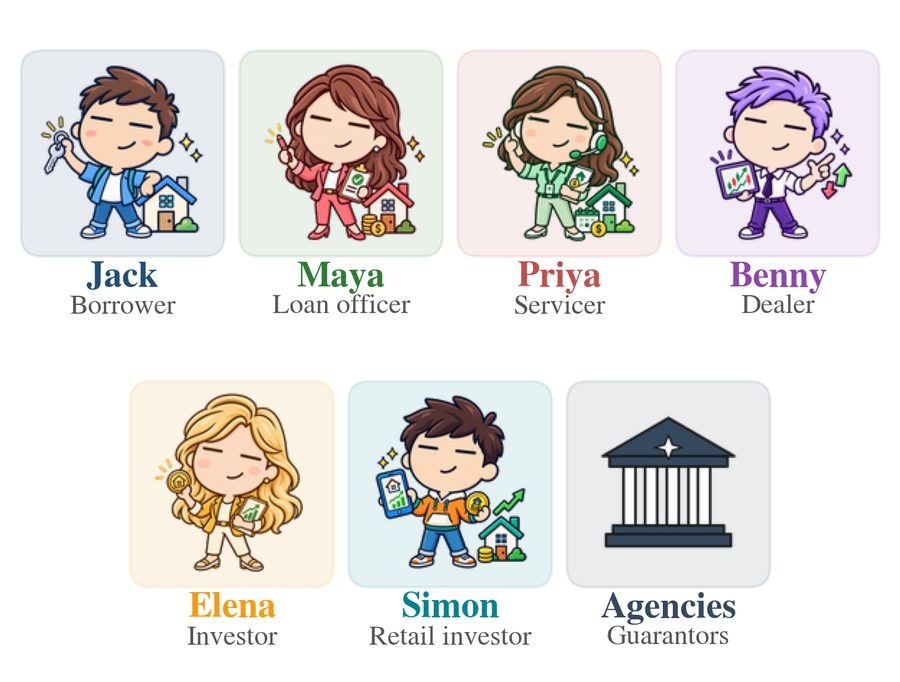
A small cast of characters recurs throughout this chapter:
 Jack: the borrower and homeowner.
 Maya: the loan officer at Wells Fargo who offers Jack the mortgage.
 Priya: the servicer who collects the payments and handles the day-to-day loan administration.
 Benny: the dealer who helps move the loan into the secondary market.
 Elena: the investor who buys the mortgage cash flow through an MBS or a TBA trade.
 Simon: the retail investor, who reaches the same cash flow through a fund or a mortgage REIT in an ordinary brokerage account.
 Fannie Mae, Freddie Mac, and Ginnie Mae: the credit guarantors: Fannie Mae and Freddie Mac act as GSE (Government-Sponsored Enterprise) wrappers that purchase loans and issue MBS themselves, while Ginnie Mae operates as a government-owned corporation that does not buy loans or issue MBS, but provides a federal timely-payment guarantee on MBS issued by approved private lenders. Each is better known by its nickname than by its charter, but the chartered abbreviations are what appear on a trading screen or in a pool file: Fannie Mae is the Federal National Mortgage Association (FNMA), Freddie Mac the Federal Home Loan Mortgage Corporation (FHLMC), and Ginnie Mae the Government National Mortgage Association (GNMA). When Elena pulls up a pool, she sees FHLMC, not Freddie Mac.